New Mega Deduction a Good Start, But More Tax Reforms Are Needed
The Federal government has unveiled a Productivity Mega Deduction, which will provide immediate expensing under Capital Cost Allowance (CCA) provisions for a broad range of depreciable property, importantly on a permanent basis, for acquisitions on or after September 15, 2026. Check out the noteworthy exclusions are listed below. This tax reform is a good start, but much more needs to be done, especially for small business owners and average taxpayers to make Canada truly competitive across our tax base.Thank You, Mr. Flaherty
 On October 9, 2009 at a presentation in Istanbul, Turkey, Canada’s Finance Minister Jim Flaherty was presented Euromoney magazine's Finance Minister of the Year award for 2009.
Grad Spotlight – New Author Kevin Gebert
 Kevin Gebert achieved his MFA-Retirement Income Specialist designation in 2006 and has since been actively involved with Knowledge Bureau, most recently publishing his first book, Financial Fotographs. We are pleased to have Kevin as one of our distinguished grads.
Scammers Victimize Immigrants Posing as CRA
 Police in Edmonton are warning of scammers who have their sights set on one Canada’s most vulnerable groups: new immigrants.
What expenses are deductible for child care costs?
 Child care expenses are claimable by Canadian residents for services provided in Canada, although deemed residents living abroad qualify as well.
Master Your Retirement: One of the Best Retirement Books in Canada
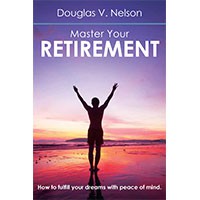 Just released in Canada, this 3rd edition of Doug Nelson’s best-selling book Master Your Retirement is receiving rave reviews.
Evelyn Jacks – Celebrity Tax Author
 As Joel Schlesinger of the Winnipeg Free Press wrote, "If there were celebrity experts on Canada's tax system, Evelyn Jacks might be one of them."