New Mega Deduction a Good Start, But More Tax Reforms Are Needed
The Federal government has unveiled a Productivity Mega Deduction, which will provide immediate expensing under Capital Cost Allowance (CCA) provisions for a broad range of depreciable property, importantly on a permanent basis, for acquisitions on or after September 15, 2026. Check out the noteworthy exclusions are listed below. This tax reform is a good start, but much more needs to be done, especially for small business owners and average taxpayers to make Canada truly competitive across our tax base.The Importance of Accurate Record Keeping
 The Tax Court of Canada (TCC) recently considered an appeal by a contractor in his 2008 and 2009 taxation years who disagreed that his motor vehicle expenses should be disallowed.
Review of CDIC Limits: Amongst Three Important Changes at the Bank
 A comprehensive review of Canada's deposit insurance framework was announced in the February 11, 2014 budget.
Evelyn Jacks: Veterans Need Tax-Efficient Investment Advice
 According to the February 11, 2014 federal budget, approximately 7,600 Canadian Armed Forces personnel leave the Canadian Armed Forces every year.
Grad Spotlight - How Kareen Is Equipped to Better Assist Her Clientele
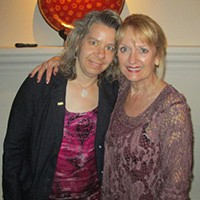 Kareen Rekowski earned her MFA-Succession and Estate Planning Specialist™ designation in 2013 and is on her way to achieving her DFA-Tax Services Specialist™ designation. We are pleased to have Kareen as one of our distinguished grads.
Be Sure to Make Your RRSP Contributions
 The deadline for making your final RRSP contribution for the 2013 tax year is quickly approaching – Monday, March 3.
Lumping Options and Stock Transactions
 I do about 200 trades a year. Can I assemble all trades into one final total instead of having to input each one, one line at a time?